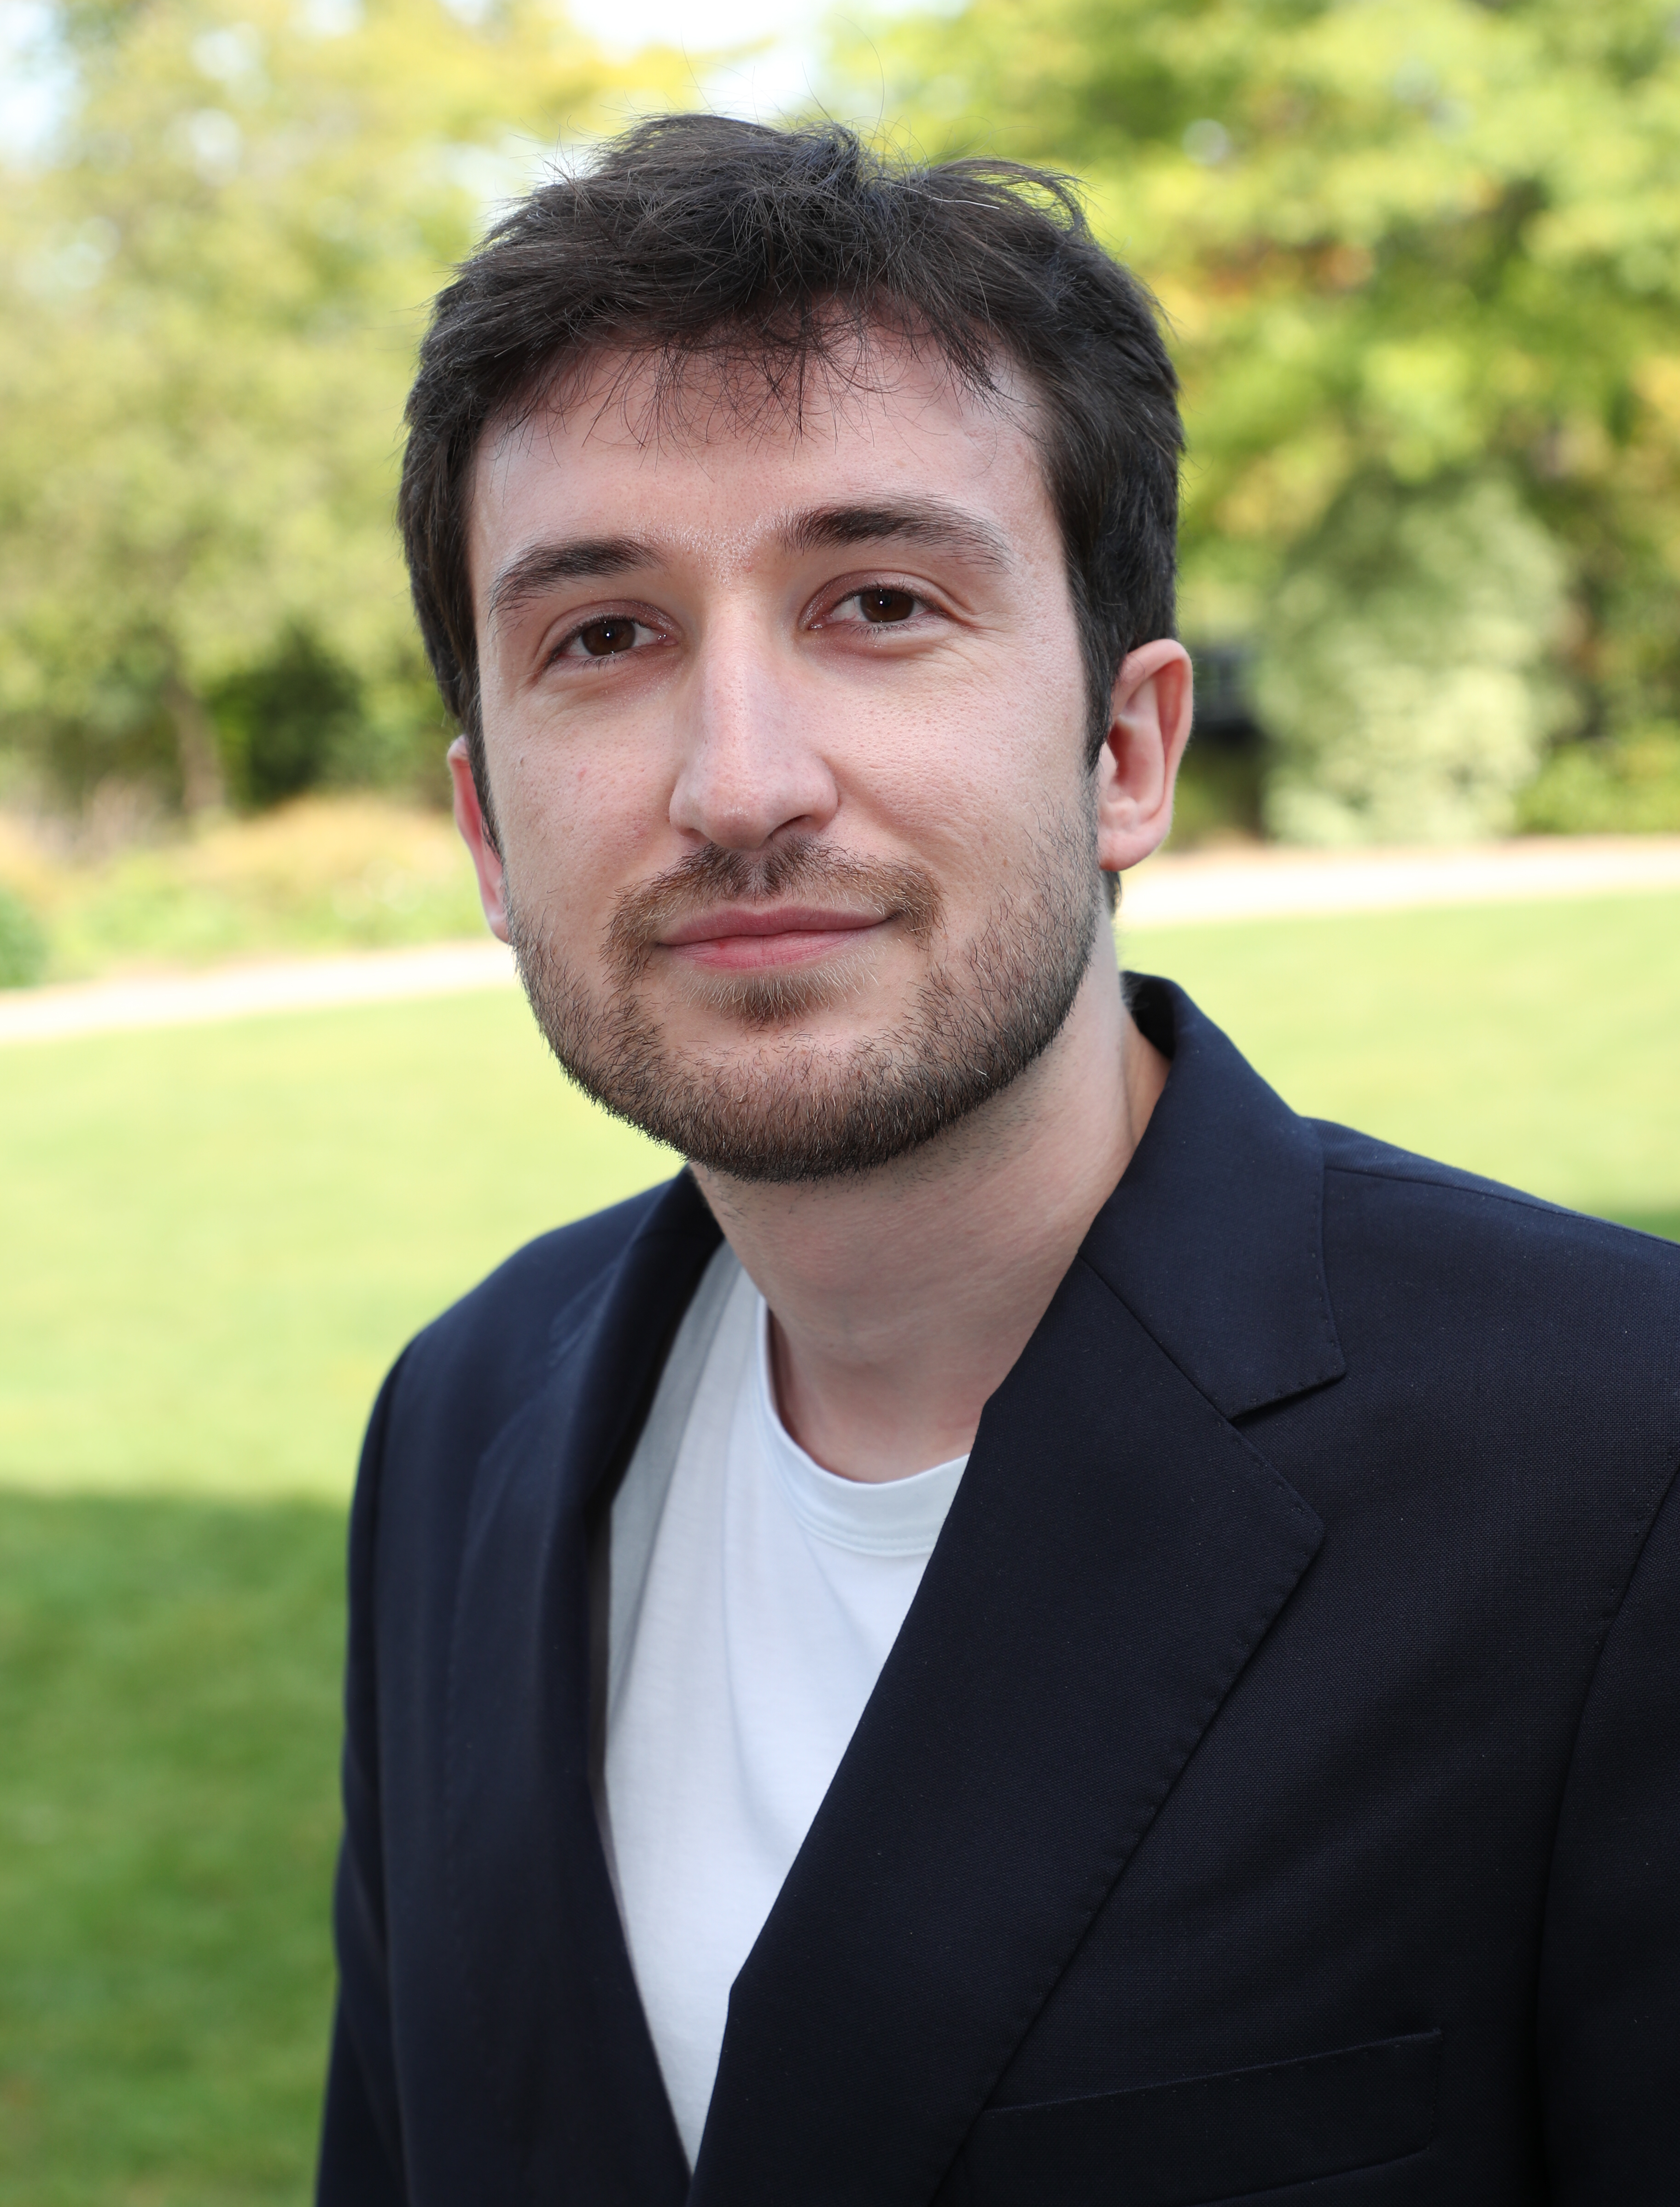
Adrien Rousset Planat
PhD student in Economics · London Business School
I am a 4th-year PhD student in Economics at London Business School. I work in macro-finance and asset pricing, using granular data to study how investors’ portfolios, trades and beliefs move prices: fund-level holdings for equity markets, 100 million EMIR-reported FX derivatives trades for exchange rates, and over a million news articles for commodity markets. My empirical work is guided by theory and relies on time-series econometrics.
News
- Jan 2026Topography of the FX Derivatives Market released as NBER Working Paper 34588.
- Nov 2025New draft of Beyond Oil: The Origins of Commodity Price Fluctuations on SSRN.
- Dec 2024Topography of the FX Derivatives Market published as Bank of England Staff Working Paper No. 1,103.
- Jul 2024Elephants in Equity Markets released as NBER Working Paper 32756.
- May 2024Started a PhD internship in the Bank of England’s International Directorate (until Feb 2025).
Research
Working Papers
-
Elephants in Equity Markets
with Hélène Rey, Vania Stavrakeva and Jenny Tang
A market-clearing decomposition of stock price growth: fund holdings covering 5% of market capitalisation account for 89% of the time variation in over 20,000 stock prices.
We introduce a novel empirical decomposition of equity price growth rates in terms of equity holdings, based on market-clearing conditions. Although our sample holdings cover only an average of 5% of market capitalization, our reconstructed equity holdings account for, on average, 89% of the time variation in over 20,000 individual stock prices and 96% of the fluctuations in 33 aggregate stock markets. Using this decomposition, we introduce new stylized facts to inform asset pricing models. We find that changes in portfolio weights explain most of the variation of individual stock prices, while aggregate wealth effects are more important for the overall stock market fluctuations. Equity markets are global and exchange rates play a key equilibrating role. They dampen local stock market volatility for all stock markets, except those associated with the three safe-haven currencies—USD, JPY, and CHF—and currencies pegged to the USD.
-
Topography of the FX Derivatives Market: A View from London
with Sinem Hacioglu-Hoke, Daniel Ostry, Hélène Rey, Vania Stavrakeva and Jenny Tang
Who hedges, who speculates and who makes markets in 100 million FX derivatives trades, and how hedge funds' speculative flows pass monetary policy shocks to exchange rates.
Drawing on 100 million transactions, we show how speculators, hedgers, and market makers interact in the world’s largest FX derivatives market, and that derivatives trading can affect exchange rates. Firms in the largest client sectors—pension and investment funds, insurers, and nonfinancials—use FX derivatives primarily to hedge currency risk, with dealer banks providing the liquidity. Hedge funds, with comparatively smaller net exposures, trade speculatively, whereas dealer banks insulate themselves from changes in speculative demand by taking offsetting positions with hedgers, especially nonfinancials. Non-bank market makers, instead, take residual exchange-rate exposures “on the margin”. Hedge funds’ speculative flows help transmit monetary policy shocks to exchange rates, while investment funds' unwinding of hedges contribute to dollar appreciations when credit risk rises. Our results highlight that exchange rates depend on the composition of trading activities in FX derivatives markets.
-
Beyond Oil: The Origins of Commodity Price Fluctuations
with Alvin Lumbanraja, Sarah Mouabbi and Evgenia Passari
Daily supply and demand proxies for 20 commodities from over a million news articles: non-oil supply disruptions move inflation and industrial production at least as strongly as oil.
Commodity supply shocks are a plausible but empirically elusive source of business-cycle fluctuations. We develop a comprehensive framework to measure them, constructing daily supply and demand proxies for 20 commodities—spanning energy, metals, agriculture, and livestock—from textual analysis of over one million news articles (2001–2023). These measures allow us to separate supply from demand across the full commodity market, not just oil. A striking finding emerges: non-oil supply disruptions affect inflation and industrial production at least as strongly as oil disturbances, a result previously undocumented in the literature. Transmission varies sharply with countries’ commodity trade positions: net importers experience more persistent output contractions and stronger inflation pass-through, while net exporters are partially insulated.
Presented at AEA, AFA, NBER Summer Institute (Asset Pricing), ECB–FRB–FRBNY Global Research Forum, CEPR ESSIM, SED, EEA–ESEM, the Federal Reserve Bank of Chicago and the ECB.
Contact
- Office
- London Business School, Regent's Park, London NW1 4SA
- Profiles
- Google ScholarLinkedInGitHub